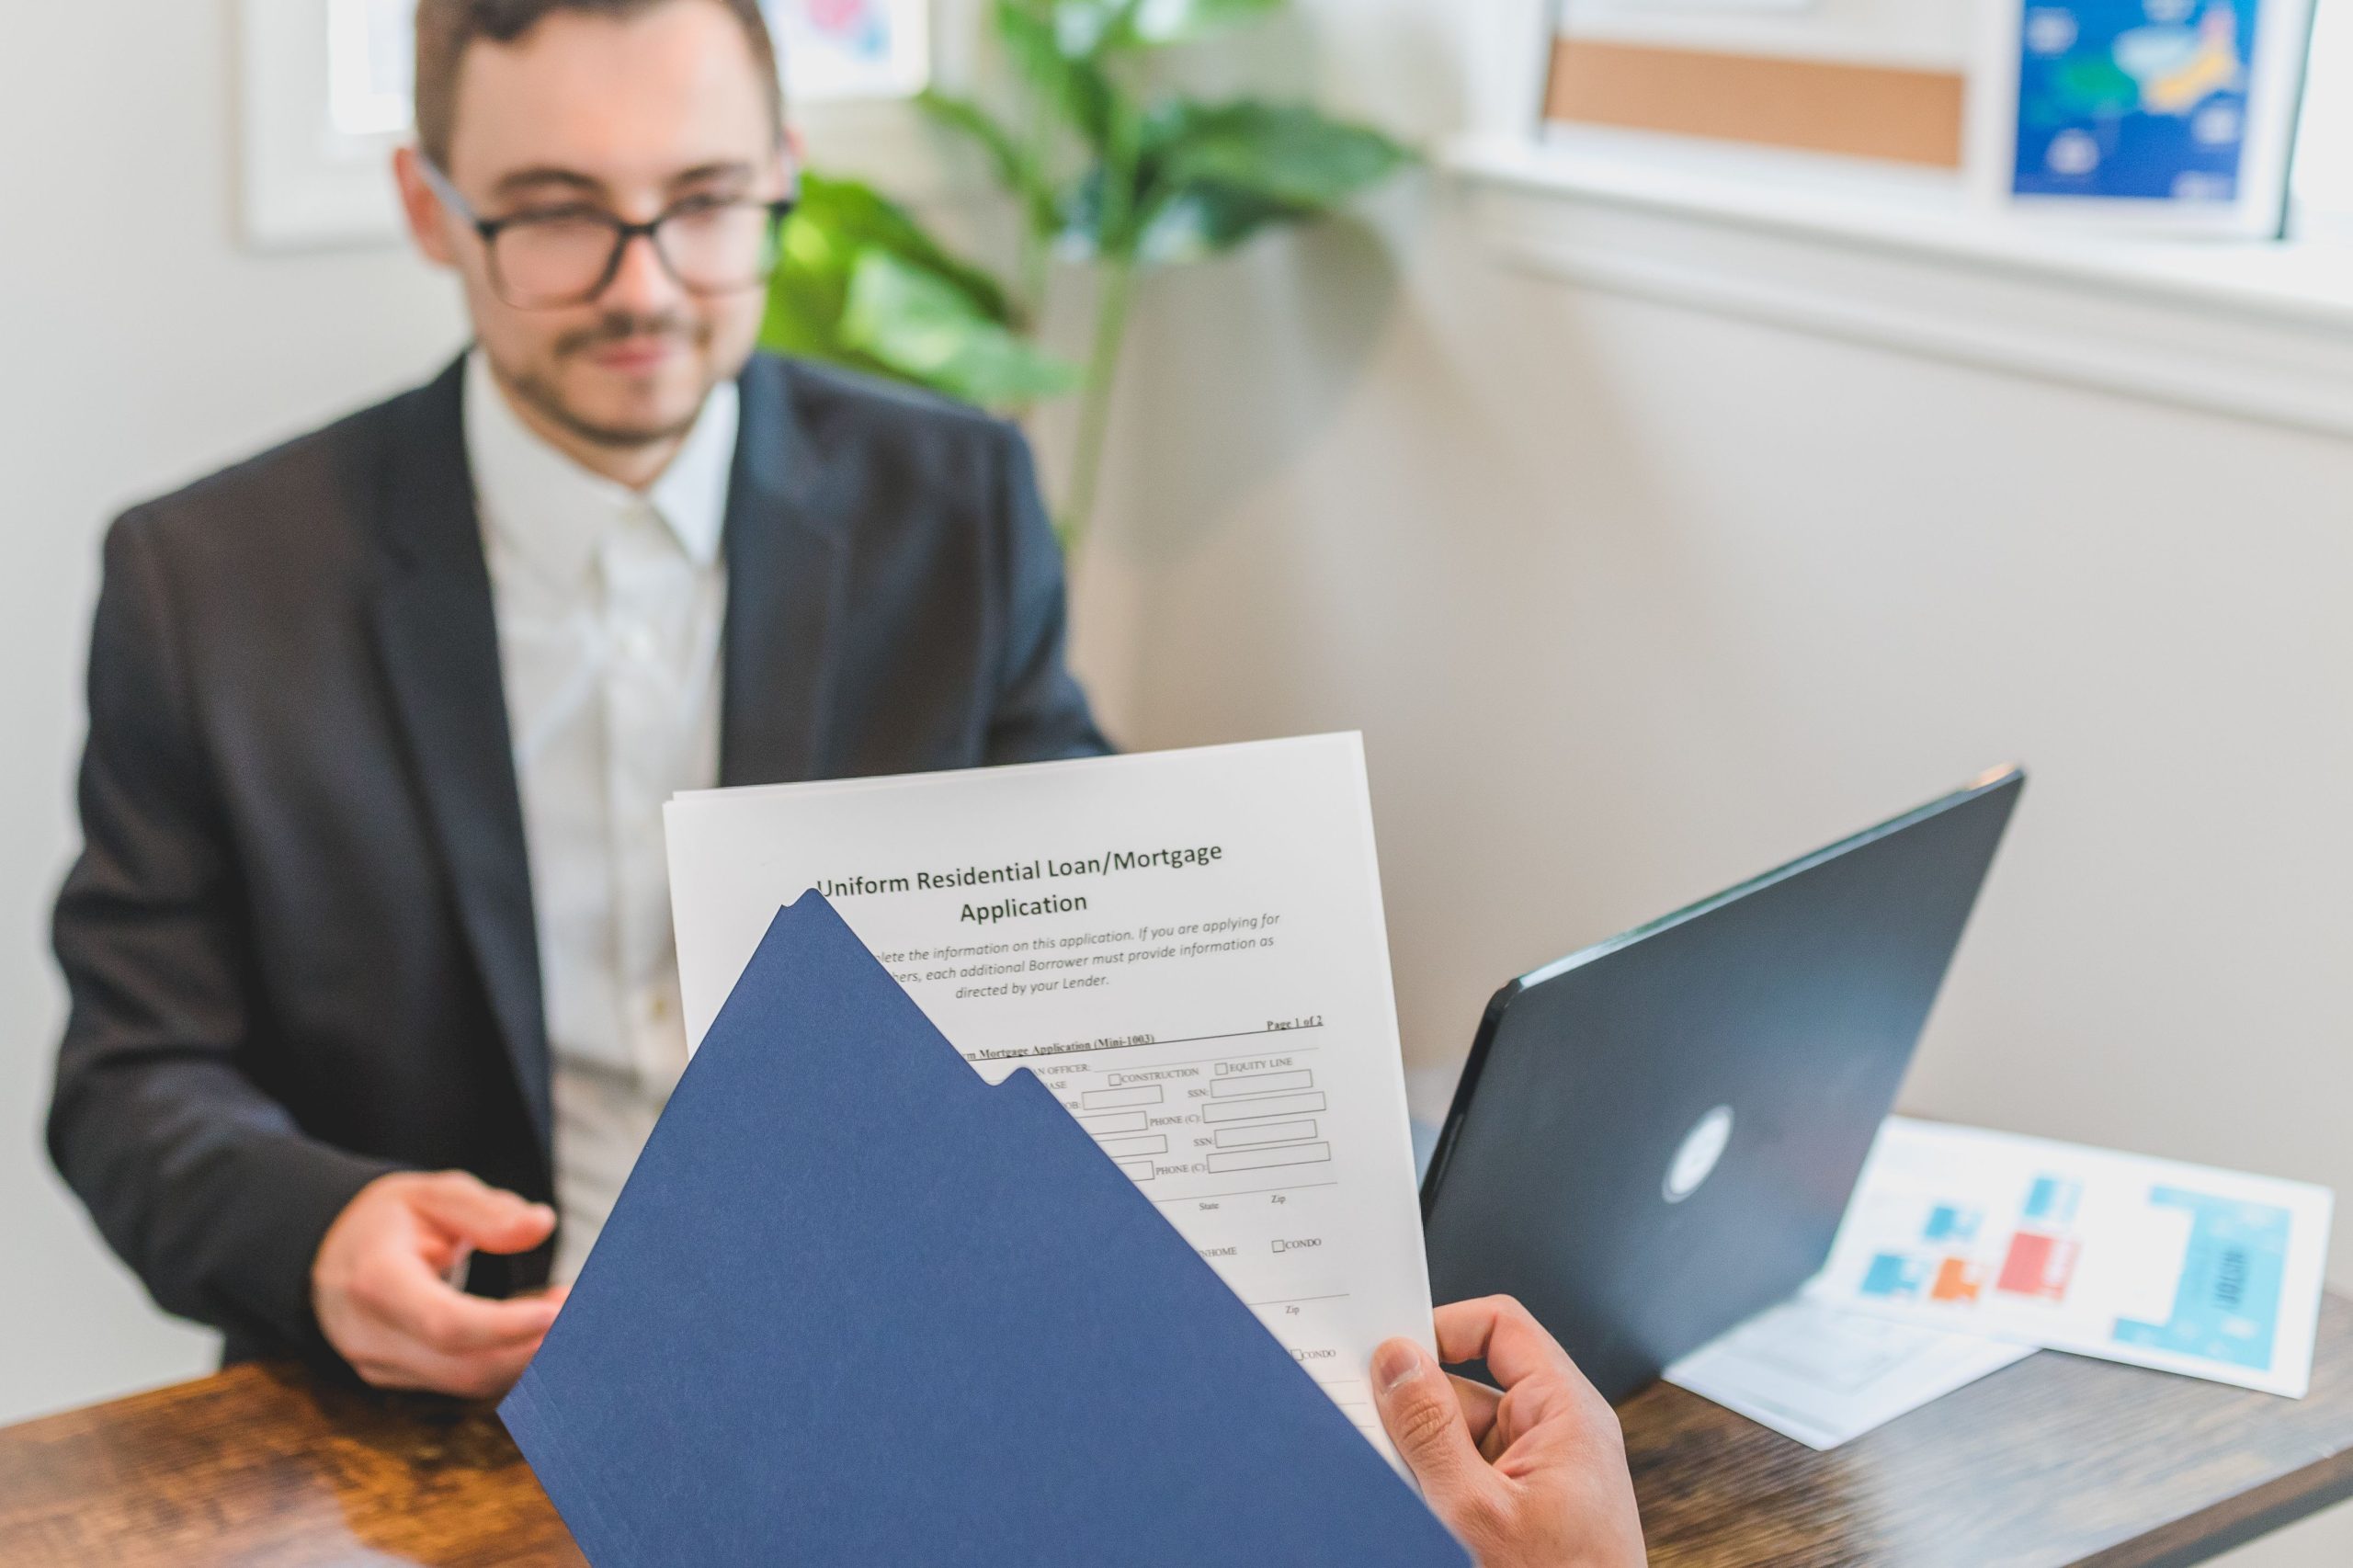
Buying a home is likely the largest financial decision you'll ever make—and one costly blunder can drain tens of thousands from your wallet. From overlooking hidden fees to ignoring your credit score, we've rounded up the seven sneaky mistakes that trip up even savvy buyers.
Advertisement
#1: Skipping the Pre-Approval Process
You might feel ready to start house hunting, but without a mortgage pre-approval in hand, you're flying blind—and sellers won't take you seriously. Pre-approval shows lenders have vetted your finances and you can actually borrow the amount you think you can. Without it, you risk falling in love with a home you can't afford, wasting time with your realtor, or losing out in a bidding war to a pre-approved buyer. This 30-minute step could save you months of frustration.
#2: Ignoring Your Credit Score

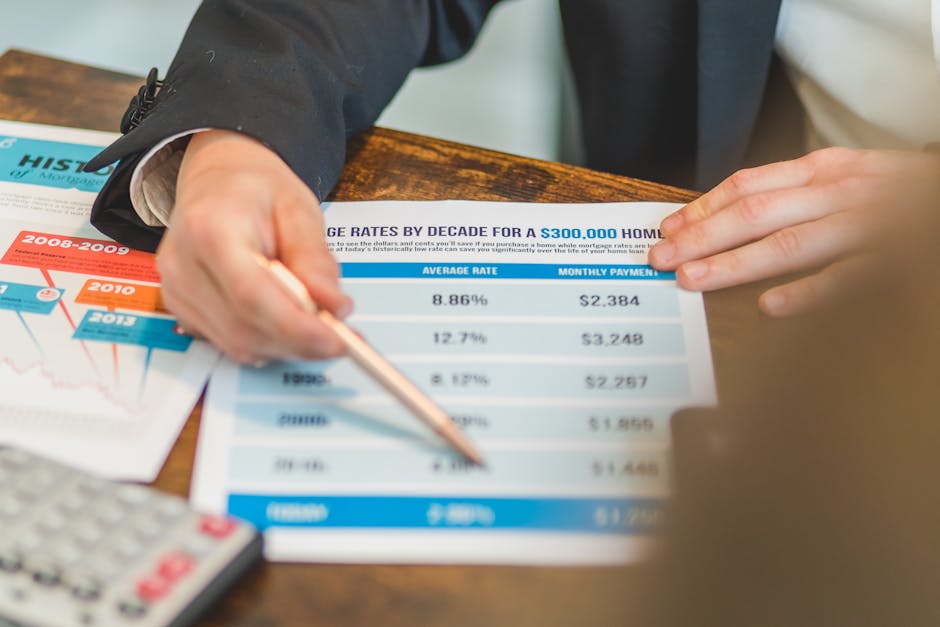
Your credit score determines the interest rate you'll pay over 30 years—and even a single percentage point difference costs you hundreds of thousands. If your score is below 740, lenders charge you more, sometimes drastically more. Most buyers don't check their score until they're ready to apply for a mortgage, but by then it's too late to fix errors or improve it. Spend a few months boosting your score before you start shopping, and you could lock in a rate that saves you $50,000 or more.
#3: Overextending Your Budget
Just because a lender approves you for $500,000 doesn't mean you should spend it. Many buyers max out their borrowing capacity and end up house-poor, with no cushion for maintenance, property taxes, or emergencies. A home also comes with unexpected costs—roof repairs, foundation issues, or plumbing emergencies can run $10,000 to $50,000 fast. Buy at 80–85% of what you're approved for, and you'll sleep better knowing you can actually afford the home alongside the rest of your life.
Advertisement
#4: Neglecting the Home Inspection

Skipping or rushing a professional home inspection to save $300–500 is a false economy that can cost you six figures. Inspectors uncover foundation cracks, failing HVAC systems, roof damage, and mold that you'll miss with your own eyes—and buyers who spot problems can renegotiate the price or walk away. Some hidden issues, like asbestos or outdated electrical wiring, take thousands to remediate. Always hire a licensed inspector and attend the walkthrough yourself; it's your last chance to catch deal-breakers before you're legally bound.
#5: Forgetting About Property Taxes and HOA Fees
Your monthly mortgage payment is only part of the cost. Property taxes, homeowners insurance, HOA dues, and PMI (if you put down less than 20%) can add $500 to $1,500 more to your monthly bill. Many buyers focus only on the mortgage rate and forget to factor in these expenses, then face a nasty surprise at closing—or worse, a budget crisis six months in. Always ask your realtor and lender for a complete breakdown of all recurring costs before you make an offer.
#6: Making Large Purchases or Changing Jobs Before Closing

Buying a car, opening new credit cards, or switching jobs between your mortgage pre-approval and closing can torpedo your loan approval. Lenders run a final credit check days before closing and review your employment and debt history again. A new car payment or a job change raises red flags and can cause lenders to pull your approval or demand a larger down payment. Even if you're tempted to upgrade your car or pursue a new opportunity, wait until after you've signed the final paperwork—your dream home isn't going anywhere.
Advertisement
#7: Underestimating Closing Costs
Closing costs typically run 2–5% of the purchase price, yet many first-time buyers are caught off guard. Costs include appraisal fees, title insurance, attorney fees, inspections, and loan origination fees—they add up to thousands and are due at closing. If you're only prepared for a down payment, you might not have cash left over for these surprises. Always get a Closing Disclosure from your lender at least three days before closing so you can review exact costs, and budget for closing expenses separately from your down payment.
Home buying mistakes aren't just costly—they can derail your purchase or lock you into a bad deal for decades. By sidestepping these seven pitfalls, you'll enter the process informed, protected, and ready to make a smart investment.
Advertisement